
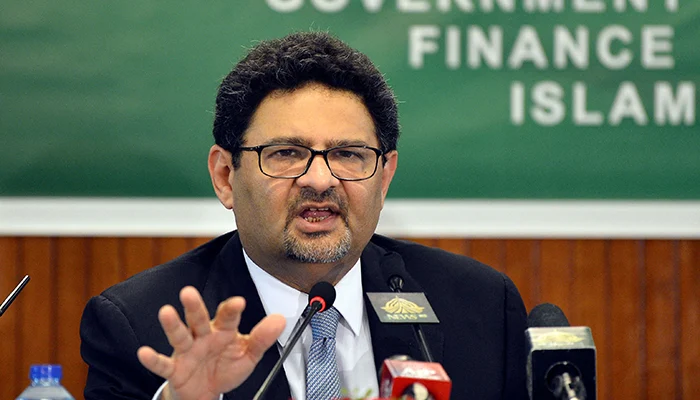
While the government waits for the rolling of three other expiring loans totaling $2 billion, China has struck a $2.3 billion commercial loan agreement with Pakistan to help its dwindling foreign exchange reserves.
Finance Minister Miftah Ismail tweeted on Wednesday, “The Chinese consortium of banks has today signed the RMB 15 billion ($2.3 billion) loan facility agreement after it was signed by the Pakistani side yesterday.”
He thanked the Chinese government for supporting this transaction and stated that the influx was anticipated to occur within a few days.
At $8.9 billion, the official forex reserves are still in the single digits. However, once Chinese banks transfer the funds, opening up closed financing channels, these loans will give it a boost.
The State Bank of Pakistan denied allegations the day before that it’s $8.9 billion in liquid foreign exchange reserves had dried up and were “fully usable.”
In the hopes of receiving the $2.3 billion commercial loan back in April, Pakistan had paid it off in March. China had, however, stipulated that the funds could not be used as a result of Pakistan’s deteriorating external sector position.
China likewise desired Pakistan to continue participating in the IMF lending program.
The IMF and the finance minister reached an agreement on the budget numbers on Tuesday, bringing the statistics into line with the global lender’s projections of income and expenses for the upcoming fiscal year.
In order to negotiate an agreement with the IMF, the administration has also agreed to some of the strict requirements.
According to Miftah, Pakistan would require a total of $41 billion in foreign loans in the upcoming fiscal year to cover a $16 billion current account deficit, repay $21 billion in maturing debt, and get additional funds to boost reserves.
To read our blog on “Agreement with IMF has been secured, Finance Minister Miftah Ismail,” click here.